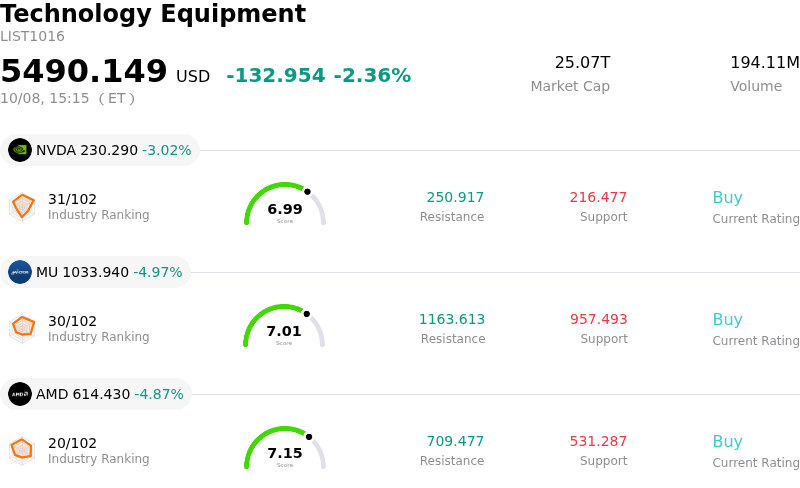
NVIDIA Corp (NVDA) moved down by 3.06%. The Technology Equipment sector is down by 2.36%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.06%; Micron Technology Inc (MU) down 4.97%; Advanced Micro Devices Inc (AMD) down 4.90%.
What is driving NVIDIA Corp (NVDA)’s stock price down today?
Nvidia experienced downward price pressure accompanied by heightened intraday volatility as profit-taking and broader macroeconomic headwinds overshadowed corporate developments. The pullback follows an extended period of outperformance and elevated valuation levels, leaving the shares sensitive to tactical trading flows and broader equity market shifts. Despite maintaining a dominant leadership position in accelerated computing and artificial intelligence infrastructure, short-term sentiment was impacted by market-wide risk-off trading.
During the session, the company announced a multi-year financial commitment aimed at building out supercomputing infrastructure, quantum computing, and scientific research initiatives across higher education and public sector cloud partners. Although this move reinforces long-term ecosystem dominance and public-private sector integration, institutional investors weighed the capital deployment against near-term free cash flow expectations. With the stock trading near historical highs, institutional trading desks frequently utilize headline-driven events as liquidity windows to realize profits and rebalance technology exposure.
Industry dynamics also contributed to intraday friction. Market participants continue to evaluate potential structural constraints in the broader technology supply chain, including regional data center power capacity limits, regulatory scrutiny surrounding major corporate acquisitions, and ongoing debate regarding the ultimate return on investment for high-volume hardware buyers. These sector-wide debates, combined with elevated option market volatility, generated wider intraday price swings across the semiconductor complex.
From an institutional research perspective, the intraday weakness reflects portfolio rebalancing rather than a structural shift in operational execution. The company continues to benefit from strong capital return programs, robust cash flow generation, and sustained demand for next-generation computing architectures. However, short-term share performance remains prone to volatility as investors continuously balance multi-year growth potential against broader macroeconomic sentiment and interest rate expectations.
Technical Analysis of NVIDIA Corp (NVDA)
Technically, NVIDIA Corp (NVDA) shows a MACD (12,26,9) value of 1.263, indicating a buy signal. The RSI at 54.198 suggests neutral condition and the Williams %R at 59.111 suggests sell condition. Please monitor closely.
Media Coverage of NVIDIA Corp (NVDA)
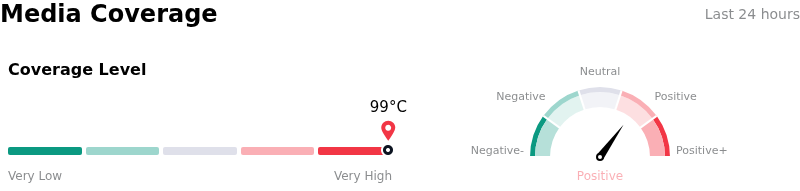
In terms of media coverage, NVIDIA Corp (NVDA) shows a coverage score of 99, indicating a very high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of NVIDIA Corp (NVDA)
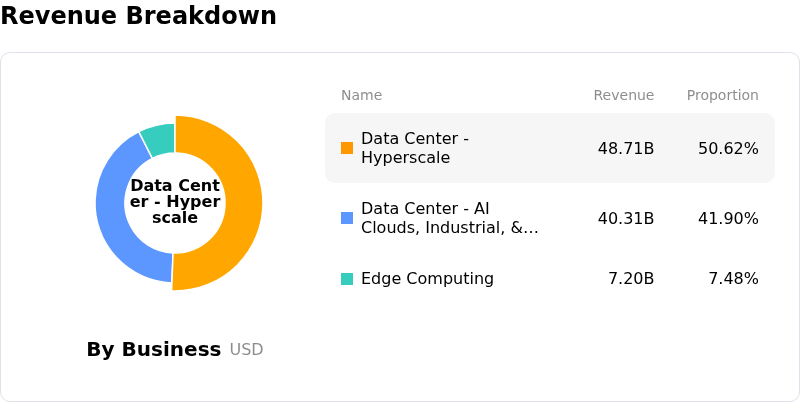
NVIDIA Corp (NVDA) is in the Technology Equipment industry. Its latest annual revenue is $215.94B, ranking 1 in the industry. The net profit is $120.07B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $324.55, a high of $515.00, and a low of $180.00.
More details about NVIDIA Corp (NVDA)
Company Specific Risks:
- Circular Financing and Customer Concentration Exposure: Recent market discussions highlight NVIDIA's commitments of nearly $50 billion to AI research labs and startups—projected to account for roughly 25% of next year's revenue—raising institutional analyst concerns regarding "circular financing" risks if these customers fail to monetize AI services or shift to in-house custom chips.
- Data Center Supply and Infrastructure Bottlenecks: Management confirmed that current supply capacity satisfies only about 70% of market demand, leaving the company exposed to execution risks as data center power grid limitations and deployment delays constrain immediate revenue growth.
- Elevated Insider Stock Dispositions: Disclosures reveal over $2 billion in insider stock sales over the past year with zero insider purchases, signaling insider caution that weighs on investor confidence and limits upside momentum near record valuation levels.
- Margin Compression and Increased Capital Obligations: Analysts project gross margins to bottom around 71% to 72% in Q4 due to rising memory costs, while new multi-year capital commitments, such as a $1 billion allocation to domestic AI and quantum initiatives, create ongoing cash flow burdens.
Find out more