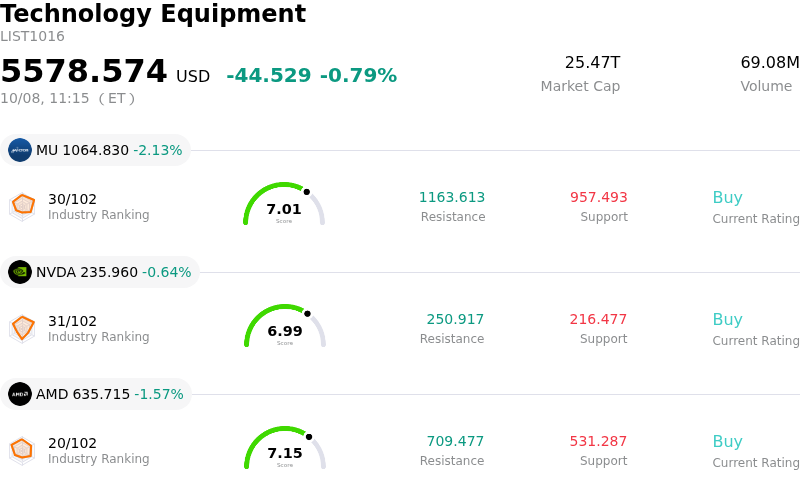
SanDisk Corporation (SNDK) moved down by 3.06%. The Technology Equipment sector is down by 0.79%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 2.13%; NVIDIA Corp (NVDA) down 0.63%; Advanced Micro Devices Inc (AMD) down 1.57%.
What is driving SanDisk Corporation (SNDK)’s stock price down today?
SanDisk Corporation experienced downward pressure amidst significant intraday trading volatility, driven primarily by profit-taking across high-performing semiconductor equities following an exceptional rally year-to-date. As market participants recalibrate positions ahead of the company's upcoming quarterly financial report later this month, institutional investors are trimming exposure to high-beta memory names. The broader technology hardware sector faced a consolidation phase as momentum traders locked in gains near recent resistance levels, accelerating selling momentum throughout the session.
Valuation considerations have increasingly entered focus for institutional portfolio managers. Following an aggressive multi-fold surge fueled by enterprise AI infrastructure adoption, High Bandwidth Flash developments, and structural NAND supply tightness, market sentiment has grown sensitive to overvaluation risks. Recent discounted cash flow models and independent valuation assessments pointing to lower medium-term fair value benchmarks have prompted cautious desk commentary, encouraging short-term tactical rotation into lower-beta assets.
Underlying fundamental demand for data-center flash storage and enterprise solid-state drives remains strong, supported by favorable memory industry conditions and upward price target revisions from several major Wall Street research teams. However, near-term sentiment friction has emerged from headlines surrounding potential competitor capacity expansions and temporary operational delays on select hyperscaler data-center buildouts. Looking ahead, institutional focus will hinge on management commentary regarding NAND pricing dynamics, supply-demand balance through the upcoming fiscal quarters, and sustained execution within the enterprise AI storage ecosystem.
Technical Analysis of SanDisk Corporation (SNDK)
Technically, SanDisk Corporation (SNDK) shows a MACD (12,26,9) value of -36.511, indicating a neutral signal. The RSI at 47.194 suggests neutral condition and the Williams %R at 93.175 suggests oversold condition. Please monitor closely.
Media Coverage of SanDisk Corporation (SNDK)
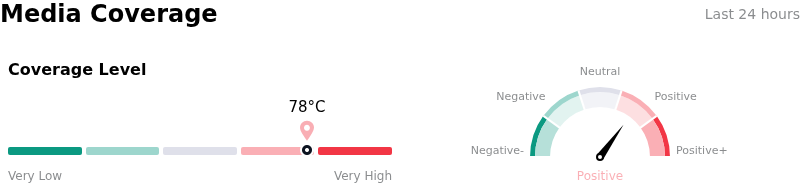
In terms of media coverage, SanDisk Corporation (SNDK) shows a coverage score of 78, indicating a high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of SanDisk Corporation (SNDK)
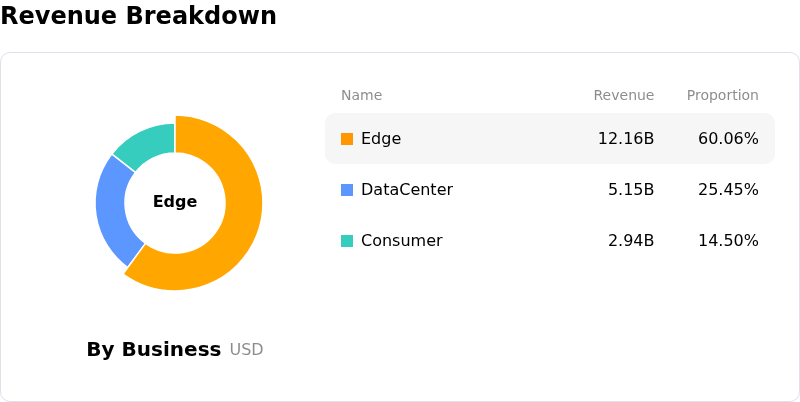
SanDisk Corporation (SNDK) is in the Technology Equipment industry. Its latest annual revenue is $20.25B, ranking 8 in the industry. The net profit is $11.43B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2143.78, a high of $3000.00, and a low of $1020.00.
More details about SanDisk Corporation (SNDK)
Company Specific Risks:
- Cyclical NAND Pricing Peak and Valuation Overextension: Despite strong recent financial performance, market commentators and institutional valuation models indicate the stock is trading significantly above modeled DCF fair value (near $1,000–$1,210 relative to the ~$1,690 market price), driven by concerns that current record gross margins reflect a temporary cyclical peak in memory pricing rather than sustainable structural pricing power.
- Competitive Capacity Expansion and Oversupply Risk: Industry reports regarding planned capacity expansions by storage competitors like Toshiba and potential wafer node additions across flash chipmakers have renewed fears of impending NAND oversupply, which could erode current pricing power and compress gross margins.
- Elevated Beta Volatility and Insider Profit-Taking: Recent trading activity shows heightened volatility (with beta estimates ranging from 3.55 to 5.23) and downside pressure from all-time highs, exacerbated by notable insider selling following the stock's multi-fold year-to-date rally.
- Hyperscaler AI Spending Concentration: Top-line expansion is heavily tied to rapid data center buildouts and agentic AI memory demand, leaving fiscal Q1 2027 revenue guidance ($10.30B–$10.80B) vulnerable to sharp pullbacks if enterprise technology spending cools or hardware deployment cycles slow down.
Find out more